Month: October 2026

23 Oct 2026

#42, Mike Harmon, Former Managing Director, Oaktree Capital Management

On this episode of the CLO Investor Podcast, Shiloh Bates sits down with Mike Harmon, author of The Financial Restructuring Tool Set: How to Fix Your Broken Balance Sheet. Mike teaches financial restructuring at Stanford and spent 21 years in Oaktree Capital’s Special Situations Group. They discuss why defaults remain elevated in a strong economy and why loan recoveries have fallen. They also look at how covenant-lite loans and liability management exercises (LMEs) have changed the restructuring playbook. Mike shares his view on rising default risk in software as AI reshapes the sector, how private credit recoveries compare with broadly syndicated loans, and why manager selection and a seat at the table matter more than ever for CLO investors.

Like & Subscribe: Amazon Music | Apple Podcasts | Spotify

09 Oct 2026

#41, Josef Pschorn, Fixed + Floating Podcast

In Episode 41 of the CLO Investor Podcast, Shiloh Bates joins Josef Pschorn of the Fixed + Floating Podcast for an in-depth discussion of today’s CLO market. They explore recent CLO equity performance, the self-healing mechanism, loan defaults and recoveries, liability management exercises, and the relative opportunities in broadly syndicated and private credit CLOs. Like & Subscribe: Amazon Music | Apple Podcasts | Spotify
08 Oct 2026

Why Are Recoveries Down?

Why First-Lien Leveraged Loan Recoveries Are Down

First-lien leveraged loans have historically been attractive for a simple reason: when a company defaults, lenders have usually recovered a meaningful portion of their investment. When I began working for CLO managers in 2000, we expected about an 80% recovery in a default. In most cases, interest income received before the default could put the lender at break-even, providing substantial downside risk protection. Investors took note and the asset class grew substantially as a result.   

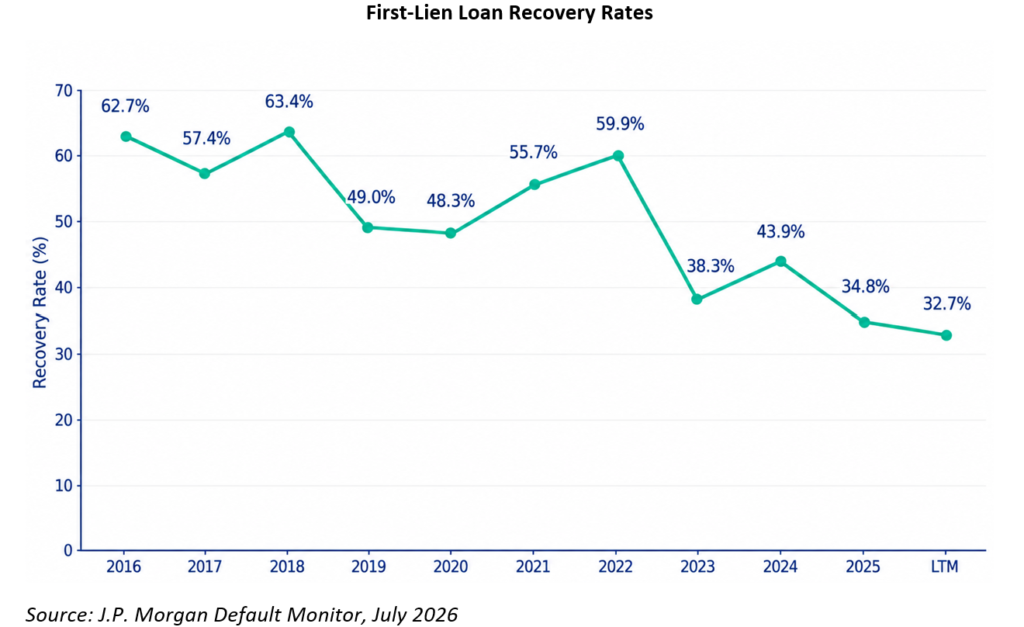
Over the past 25 years, first-lien recoveries have averaged only 61%, with a substantial downward trend in recent years. According to J.P. Morgan, the average recovery rate for first-lien loans on June 30, 2026 was 33%, much closer to levels historically associated with second-lien debt or high yield bonds.

To understand why, we need to go back to the success of the asset class itself. Strong historical performance attracted some investors while years of near-zero interest rates after the Global Financial Crisis increased demand from investors searching for yield. The U.S. leveraged loan market grew from about $500 billion in 2010 to roughly $1.5 trillion by the end of 2025 as CLOs, loan funds and other institutions became dependable sources of financing.

When more capital is competing to lend, borrowers can negotiate for more leverage, lower spreads and more favorable financing terms. Over time, negotiating power shifted away from lenders, contributing to two changes that now weigh on loan recoveries: higher loan-to-value capital structures and weaker loan documentation.

Before the Global Financial Crisis, the initial senior secured loan-to-value was lower, with the remainder of the leveraged buyout financed with equity and junior debt. Today, many capital structures are loan-only, done at approximately 50% loan-to-value. The initial difference in loan-to-value is material for loan recoveries. First-lien lenders are now the first debt to absorb losses once the equity is gone. 

The second change is the quality of the loan documentation. More than 90% of the broadly syndicated loan market is now covenant-lite compared to roughly 20% in 2007. A covenant-lite loan does not require the borrower to pass financial tests like maximum leverage or minimum interest coverage. A covenant breach can require negotiations between the borrower and its lenders while the company still has liquidity and enterprise value. Without financial covenants, lenders may not gain influence until performance has declined to the point where a favorable recovery isn’t possible.

Weaker loan documentation can also give borrowers more freedom to incur debt, move assets outside the collateral package, or favor one group of lenders over another. This flexibility has led to an increase in out-of-court restructurings called liability management exercises (LMEs). Weaker loan documentation is often overlooked when loans are syndicated, especially when deals are oversubscribed. Additionally, the lenders don’t expect the loose terms to come into play – they expect the business to grow its profits and repay the debt without issue. But if the business underperforms, the legal terms of the loan documentation will matter a great deal. 

An increased supply of leveraged loans, or a reduction in investor demand for leveraged loans, has the potential to shift the dynamic back in the lenders’ favor. Until then, investors should be cautious about assuming that the favorable recoveries of the past will repeat in the future.
DISCLOSURES

Past performance is not indicative of future results.

This is not an invitation to make any investment or purchase shares in any fund and is intended for informational purposes only. Nothing contained herein constitutes investment, legal, tax or other advice, nor is it to be relied on in making an investment or other decision. Nothing herein should be construed as a solicitation, offer or recommendation to acquire or dispose of any investment, or to engage in any other transaction.

For further information feel free to email info@flatrockglobal.com


01 Oct 2026

What are CLO ETFs?