Author: Shiloh Bates

Shiloh Bates, CFA joined Flat Rock Global in 2018 and is a Partner and Chief Investment Officer. Prior to that, he was a Managing Director at Benefit Street Partners. During his 20-year career, Mr. Bates has worked for several CLO managers and has been one of the largest investors in CLO securities. He wrote the book, CLO Investing with a focus on CLO Equity and BB Notes. He is also the host of the CLO Investor Podcast. Shiloh has a BA from Virginia Tech in Political Science, an MA in Public Policy from Harvard University, an MA in Financial Mathematics from the University of Chicago, and an MA in Statistics from Columbia University. He was also a specialist in psychological warfare in the US Army Reserves.
09 Oct 2026

#41, Josef Pschorn, Fixed + Floating Podcast

In Episode 41 of the CLO Investor Podcast, Shiloh Bates joins Josef Pschorn of the Fixed + Floating Podcast for an in-depth discussion of today’s CLO market. They explore recent CLO equity performance, the self-healing mechanism, loan defaults and recoveries, liability management exercises, and the relative opportunities in broadly syndicated and private credit CLOs. Like & Subscribe: Amazon Music | Apple Podcasts | Spotify
08 Oct 2026

Why Are Recoveries Down?

Why First-Lien Leveraged Loan Recoveries Are Down

First-lien leveraged loans have historically been attractive for a simple reason: when a company defaults, lenders have usually recovered a meaningful portion of their investment. When I began working for CLO managers in 2000, we expected about an 80% recovery in a default. In most cases, interest income received before the default could put the lender at break-even, providing substantial downside risk protection. Investors took note and the asset class grew substantially as a result.   

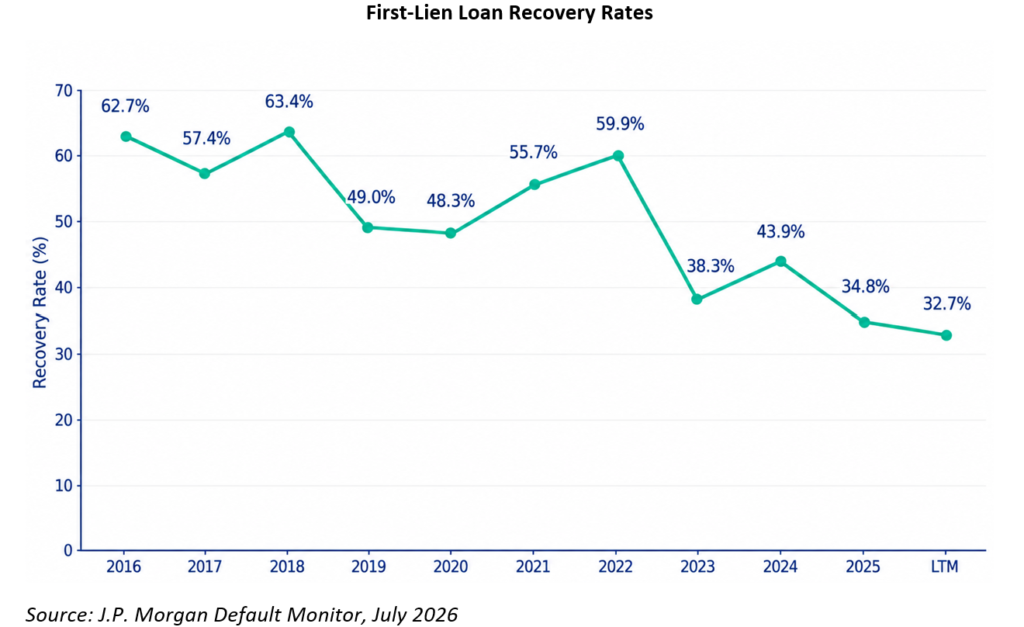
Over the past 25 years, first-lien recoveries have averaged only 61%, with a substantial downward trend in recent years. According to J.P. Morgan, the average recovery rate for first-lien loans on June 30, 2026 was 33%, much closer to levels historically associated with second-lien debt or high yield bonds.

To understand why, we need to go back to the success of the asset class itself. Strong historical performance attracted some investors while years of near-zero interest rates after the Global Financial Crisis increased demand from investors searching for yield. The U.S. leveraged loan market grew from about $500 billion in 2010 to roughly $1.5 trillion by the end of 2025 as CLOs, loan funds and other institutions became dependable sources of financing.

When more capital is competing to lend, borrowers can negotiate for more leverage, lower spreads and more favorable financing terms. Over time, negotiating power shifted away from lenders, contributing to two changes that now weigh on loan recoveries: higher loan-to-value capital structures and weaker loan documentation.

Before the Global Financial Crisis, the initial senior secured loan-to-value was lower, with the remainder of the leveraged buyout financed with equity and junior debt. Today, many capital structures are loan-only, done at approximately 50% loan-to-value. The initial difference in loan-to-value is material for loan recoveries. First-lien lenders are now the first debt to absorb losses once the equity is gone. 

The second change is the quality of the loan documentation. More than 90% of the broadly syndicated loan market is now covenant-lite compared to roughly 20% in 2007. A covenant-lite loan does not require the borrower to pass financial tests like maximum leverage or minimum interest coverage. A covenant breach can require negotiations between the borrower and its lenders while the company still has liquidity and enterprise value. Without financial covenants, lenders may not gain influence until performance has declined to the point where a favorable recovery isn’t possible.

Weaker loan documentation can also give borrowers more freedom to incur debt, move assets outside the collateral package, or favor one group of lenders over another. This flexibility has led to an increase in out-of-court restructurings called liability management exercises (LMEs). Weaker loan documentation is often overlooked when loans are syndicated, especially when deals are oversubscribed. Additionally, the lenders don’t expect the loose terms to come into play – they expect the business to grow its profits and repay the debt without issue. But if the business underperforms, the legal terms of the loan documentation will matter a great deal. 

An increased supply of leveraged loans, or a reduction in investor demand for leveraged loans, has the potential to shift the dynamic back in the lenders’ favor. Until then, investors should be cautious about assuming that the favorable recoveries of the past will repeat in the future.
DISCLOSURES

Past performance is not indicative of future results.

This is not an invitation to make any investment or purchase shares in any fund and is intended for informational purposes only. Nothing contained herein constitutes investment, legal, tax or other advice, nor is it to be relied on in making an investment or other decision. Nothing herein should be construed as a solicitation, offer or recommendation to acquire or dispose of any investment, or to engage in any other transaction.

For further information feel free to email info@flatrockglobal.com


01 Oct 2026

What are CLO ETFs?

17 Sep 2026

#40 Part 2, Chris Gilbert, Co-Head of Securitized Products, Natixis

This episode is part two of Shiloh Bates’ conversation with Chris Gilbert, Co-head of the Securitized Products Group at Natixis. Where the first part covered CLO debt ratings, this episode digs into CLO refinancings and resets — comparing the two options, walking through the economics and payback analysis on refis, and discussing how resets let a manager rebuild the capital structure, extend the reinvestment period, and clean up the portfolio.

Like & Subscribe: Amazon Music | Apple Podcasts | Spotify

03 Sep 2026

#39 Part 1, Chris Gilbert, Co-Head of Securitized Products, Natixis

In this episode of the CLO Investor Podcast, Shiloh Bates sits down with Chris Gilbert, Co-Head of Securitized Products at Natixis, to explore how CLO debt tranches are rated and examine proposed methodology changes from Fitch and Moody’s. The discussion breaks down the mechanics behind CLO ratings, the potential impact of updated rating criteria on CLO investors and issuers, and how regulatory developments such as NAIC capital rules may influence demand across different parts of the CLO capital structure.

Like & Subscribe: Amazon Music | Apple Podcasts | Spotify

12 Aug 2026

#38, Sam Garza, Portfolio Manager, DoubleLine

In this episode of the CLO Investor Podcast, Shiloh Bates sits down with Sam Garza, Portfolio Manager at DoubleLine, to discuss the evolving CLO market. They explore why CLO debt continues to offer attractive relative value, the challenges facing CLO equity investors, the rise of captive CLO equity funds, and the difference between broadly syndicated and private credit CLOs. The conversation also covers software loan exposure, the impact of AI on credit markets, higher-for-longer interest rates, and proposed rating agency changes that could reshape CLO structures and investor protections.

Like & Subscribe: Amazon Music | Apple Podcasts | Spotify

07 Jul 2026

#37, David Altenhofen, Head of Credit Management, Accunia Credit Management

David Altenhofen, Head of Credit Management at Accunia Credit Management, joins The CLO Investor podcast to compare the US and European CLO markets, digging into topics like manager selection and alpha, CLO equity’s recent struggles, software loan exposure, and a rare European CLO single-B default. Like & Subscribe: Amazon Music | Apple Podcasts | Spotify
06 Jul 2026

Are CLO BB Notes Misrated?

23 Jun 2026

#36, Laila Kollmorgen, Global Head of CLO Tranche Investing, MetLife Investment Management

Laila Kollmorgen, Global Head of CLO Tranche Investing at MetLife Investment Management, joins The CLO Investor podcast to discuss her investment approach across the CLO capital structure and the products her team manages. Laila shares why she currently sees compelling opportunities in CLO equity, junior BBBs, and AAAs, while offering insights on software credit risk, AI disruption, private credit, and the evolving outlook for leveraged loans and CLOs. Like & Subscribe: Amazon Music | Apple Podcasts | Spotify